Can you finance a moved manufactured home?
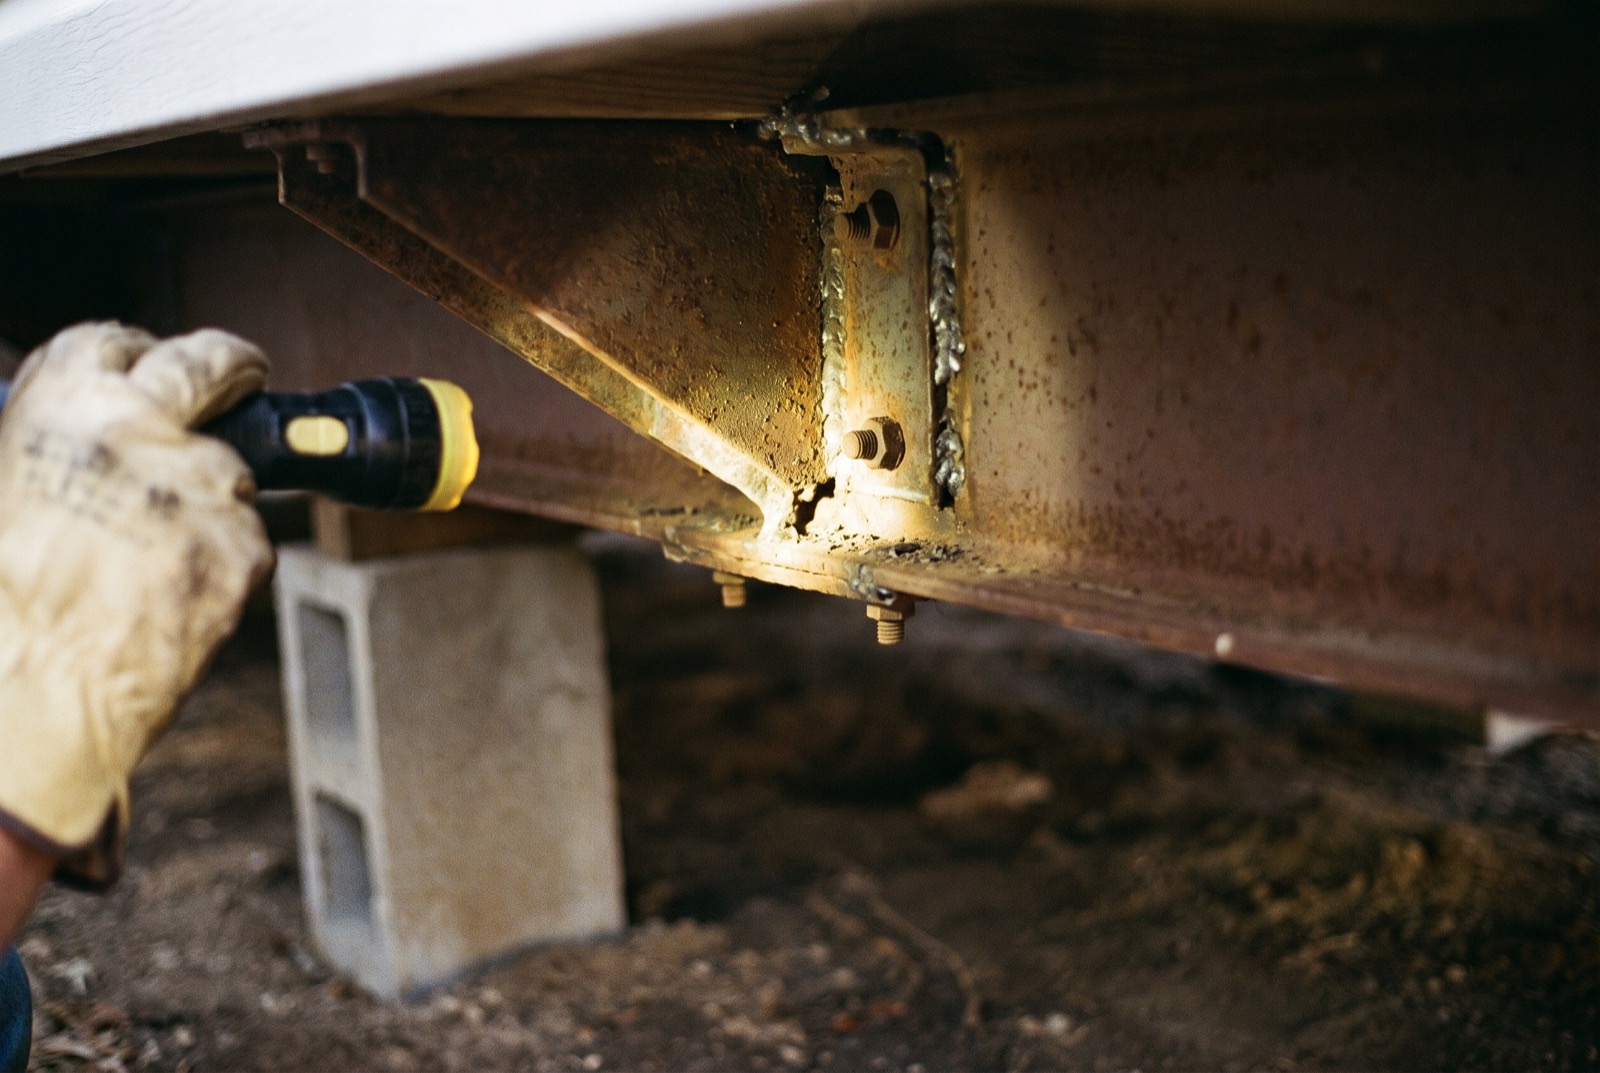
Sometimes, but your lender decides, and the answer depends on the loan program and the details of your file. A lender may ask for a structural report from a Professional Engineer who inspects the home where it sits now.
Why does a move matter to a lender?
A home that was transported and set up again has been through stress that a home left in place has not. A lender may want evidence that the structure came through the move in sound condition.
That evidence usually arrives as a written engineering request tied to your specific loan, so ask for it in writing.
Has anything changed for moved homes?
A recent change from Freddie Mac permits qualifying relocated manufactured homes, subject to conditions. That applies to mortgages sold to Freddie Mac.
It does not clear a condition on another program. If your file is an FHA file, it still follows the requirements your lender gives you for FHA, and a change of program can change the questions the lender needs answered.
What might your lender ask for?
Every file is different, but a request may include:
- A structural integrity assessment after the move, signed by an engineer.
- A foundation certification, which is a separate document.
- Installation, transport, or permit records, if they exist.
- Records that identify the home, such as the HUD label and data plate.
For what the first item covers, read what is a structural integrity report.
Is a foundation certification enough?
Not necessarily. A foundation certification looks at the foundation against specified criteria, while a request about a relocated home's structural integrity may call for an assessment beyond the foundation.
Do not assume one document replaces the other. Send the lender's full wording so the work is scoped to what the lender actually asked for.
Does a report guarantee approval?
No. The report documents the structural condition of the home. The lender reviews the whole file, including the loan itself, and decides whether the home and the loan meet its requirements.
We cannot promise that a particular home or loan will qualify, and anyone who does is promising something that is not theirs to promise.
Where do you start?
Ask your loan officer which loan program is being reviewed and for the engineering condition in writing. Our structural integrity report service is built for this request.
Reports are signed by a Professional Engineer licensed in the state where the home sits: Missouri, Arkansas, Illinois, Kansas, Iowa, Nebraska, or Indiana for us.
Send the address, what you know about the move, and your lender's wording. We reply within one business day.